Are Your 401(k) and Retirement Accounts Divided in a Georgia Divorce?
For many couples, retirement savings are among their most valuable assets. Whether you have a 401(k), an IRA, or a pension, you may be wondering what will happen to those savings if you get divorced. One of the most common questions is whether your spouse can receive part of a retirement account that’s held entirely in your name.
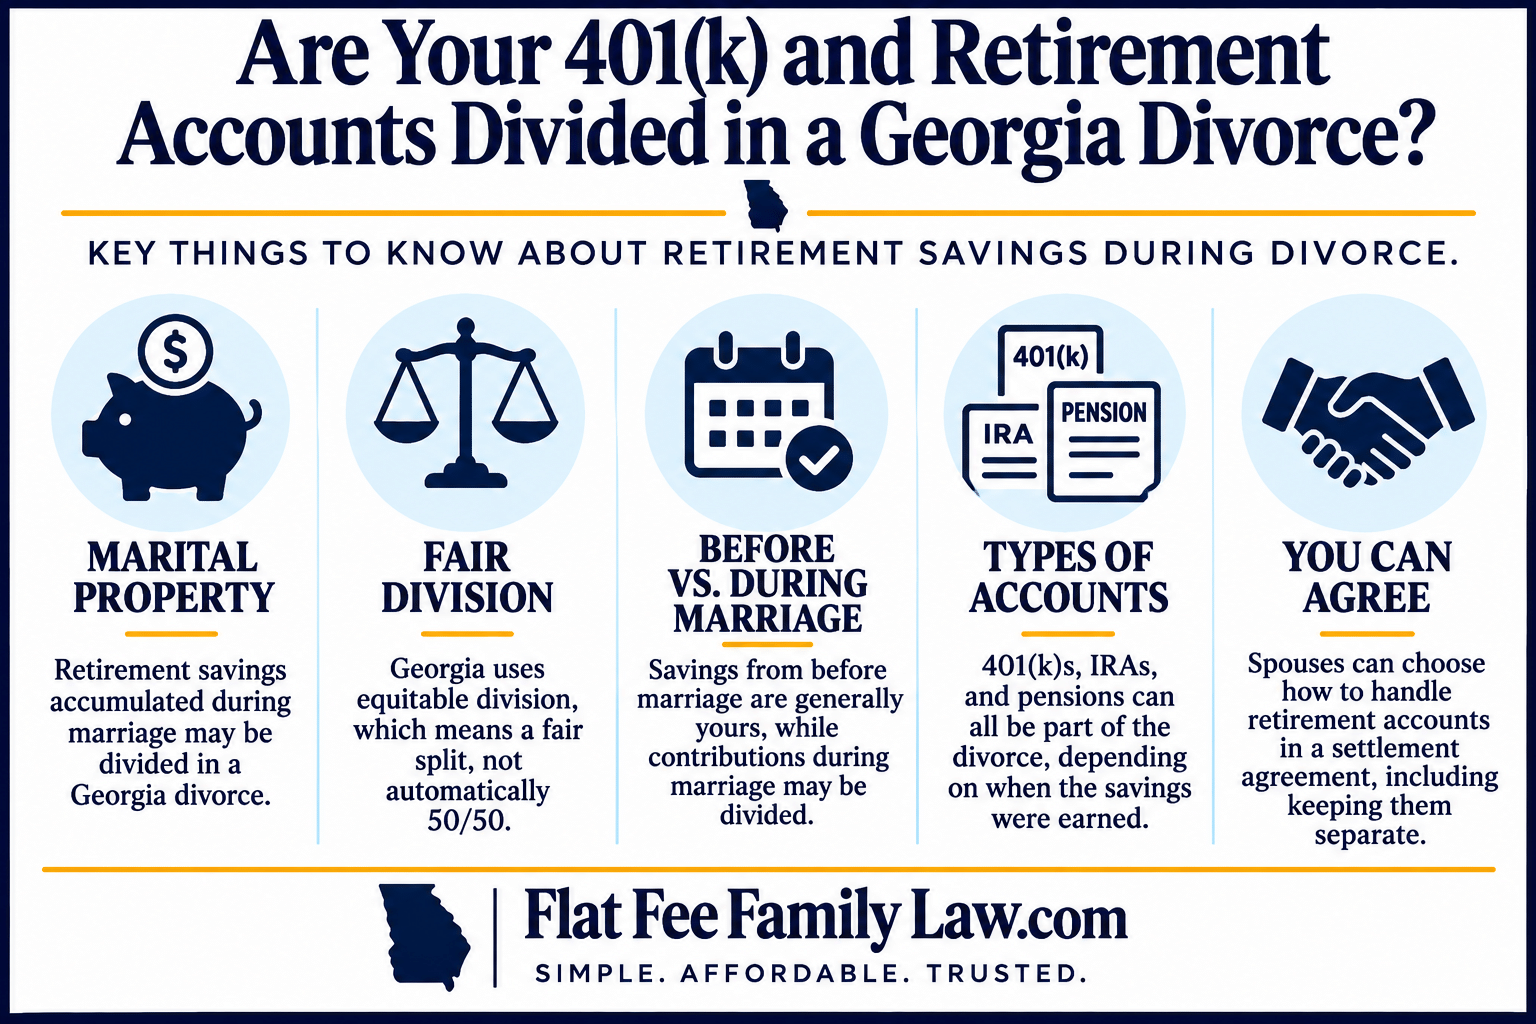
In Georgia, retirement savings accumulated during marriage may be divided during divorce. However, that doesn’t automatically mean your spouse is entitled to half of everything you’ve saved. Understanding a few basic rules can help you make informed decisions about your financial future.
Are Retirement Accounts Considered Marital Property in Georgia?
Yes. Retirement savings accumulated during marriage are generally considered marital property, even if the account is only in one spouse’s name. Georgia follows a principle called equitable division, which means marital property is divided fairly based on the circumstances. It does not necessarily mean everything is divided equally.
For example, if you contributed to a 401(k) throughout a 15-year marriage, the money accumulated during those years may be considered marital property. The same generally applies to retirement contributions made by your employer and pension benefits earned while you were married. However, identifying retirement savings as marital property doesn’t automatically determine how much each spouse will receive.
Is Your Spouse Automatically Entitled to Half of Your Retirement Accounts?
No. Georgia does not require retirement accounts to be divided 50/50.
Retirement savings are considered alongside other marital assets, such as your home, vehicles, savings accounts, and investments. For example, one spouse might receive a larger share of the marital home’s equity while the other keeps more of the retirement savings.
Couples may also agree to divide certain retirement accounts while leaving others with their existing owners. The goal is a fair overall division of marital property, not necessarily an equal split of every individual asset.
What Happens to Your 401(k), IRA, or Pension During Divorce?
Different retirement accounts work differently, but the general question is the same: how much of the retirement savings was accumulated during the marriage?
401(k) Accounts
A 401(k) is a retirement savings account offered through an employer. Money contributed during marriage, including employer matching contributions, may be considered marital property. If the spouses agree to divide a 401(k), or a court orders it divided, a separate court order may be needed to instruct the retirement plan on how to distribute the funds.
Individual Retirement Accounts (IRAs)
Traditional and Roth IRAs may also be divided during divorce. As with a 401(k), money contributed during marriage may be considered marital property, even if the account is held in only one spouse’s name. IRAs generally follow a different transfer process than employer-sponsored retirement accounts.
Pension Benefits
Pensions provide retirement income, often through monthly payments after an employee retires. Even if those payments won’t begin for several years, pension benefits earned during marriage may be considered marital property. If you worked for an employer both before and during your marriage, only part of your pension may be subject to division. The specific rules depend on the retirement plan and the circumstances of your marriage.
What If You Had Retirement Savings Before Getting Married?
Retirement savings accumulated before marriage are generally considered separate property in Georgia. However, having an account before marriage doesn’t necessarily mean the entire account remains separate.
For example, suppose you had $50,000 in a 401(k) when you got married. Over the next 10 years, you continued contributing to the account, your employer added matching contributions, and the investments grew. By the time you divorce, the account is worth $200,000. The money you had before marriage may remain separate property, while contributions made during marriage and some of the investment growth may be considered marital property. Importantly, not all investment growth is automatically marital property. Growth attributable to your premarital savings may remain separate.
Determining which portion belongs to each category may require reviewing older account statements and contribution records. This is one reason it’s important to understand your retirement account balances before agreeing to a divorce settlement.
Can You and Your Spouse Agree to Keep Your Own Retirement Accounts?
Yes. Spouses can agree to keep their individually held retirement accounts as part of their overall divorce settlement. For example, one spouse may keep the marital home while the other retains more retirement savings. Or both spouses may agree that each will keep the retirement accounts in their own name.
These arrangements can be part of an uncontested divorce, provided the spouses agree on the financial terms and other issues necessary to resolve their case. However, retirement accounts may have different tax consequences than other assets. A retirement account worth $100,000 may not provide the same spendable value as $100,000 in cash. Before signing an agreement, it’s important to understand what you’re receiving and what you may be giving up.
What Happens if You Disagree About Dividing Retirement Savings?
Disagreements about retirement accounts are not uncommon, particularly when one spouse had substantial savings before marriage, or the couple disagrees about how much of an account should be divided.
For example, one spouse may believe a retirement account should remain entirely theirs because it’s in their name, while the other believes the savings accumulated during marriage should be shared. These disagreements may be resolved through negotiations or mediation. If the spouses cannot reach an agreement, the court may need to decide which retirement savings are marital property and how they should be divided.
Divorce Representation for Retirement and Property Division in Georgia
Retirement savings may represent decades of work and financial planning. Understanding how those savings may be affected by divorce can help you make decisions that protect your financial future. At Flat Fee Family Law, attorney Brendan Dalton represents clients throughout Georgia in uncontested and contested divorce cases, including matters involving retirement accounts, property division, and financial disagreements.
Our flat-fee divorce services include:
- Uncontested Divorce — $2,000, including standard filing fees.
- Full-Case Divorce Representation — $3,500 to respond to a divorce petition or $4,200 to file.
Our full-case representation covers attorney services through completion of the agreed case, including negotiations, settlement discussions, and court proceedings as needed. Certain third-party expenses may not be included and are addressed in the service agreement. Clients work directly with Brendan and know their attorney fees before representation begins.
No retainers. No hourly billing. No surprises.
If you’re considering divorce and have questions about your retirement savings or your spouse’s retirement benefits, schedule a consultation with Flat Fee Family Law to discuss your circumstances and legal options.
Frequently Asked Questions About Retirement Accounts in a Georgia Divorce
Is my spouse entitled to half of my 401(k) in a Georgia divorce?
Not automatically. Retirement savings accumulated during marriage may be divided, but Georgia does not require every retirement account to be split equally.
Can my spouse receive retirement savings I had before marriage?
Retirement savings accumulated before marriage are generally separate property. However, contributions made during marriage and certain increases in value may be considered marital property.
Does it matter whose name is on the retirement account?
Not necessarily. Retirement savings accumulated during marriage may be considered marital property even if the account is held in only one spouse’s name.
Do you need a special court order to divide a 401(k)?
Often, yes. Many 401(k) plans require a separate court order, called a Qualified Domestic Relations Order (QDRO), before retirement benefits can be divided. Your attorney can help explain whether one is needed for your particular plan.
Can we agree not to divide our retirement accounts?
Yes. Spouses may agree to keep their own retirement accounts as part of their divorce settlement. The agreement should clearly explain how the retirement assets will be handled.